After the Business Exit: Why the Descent Needs a Plan
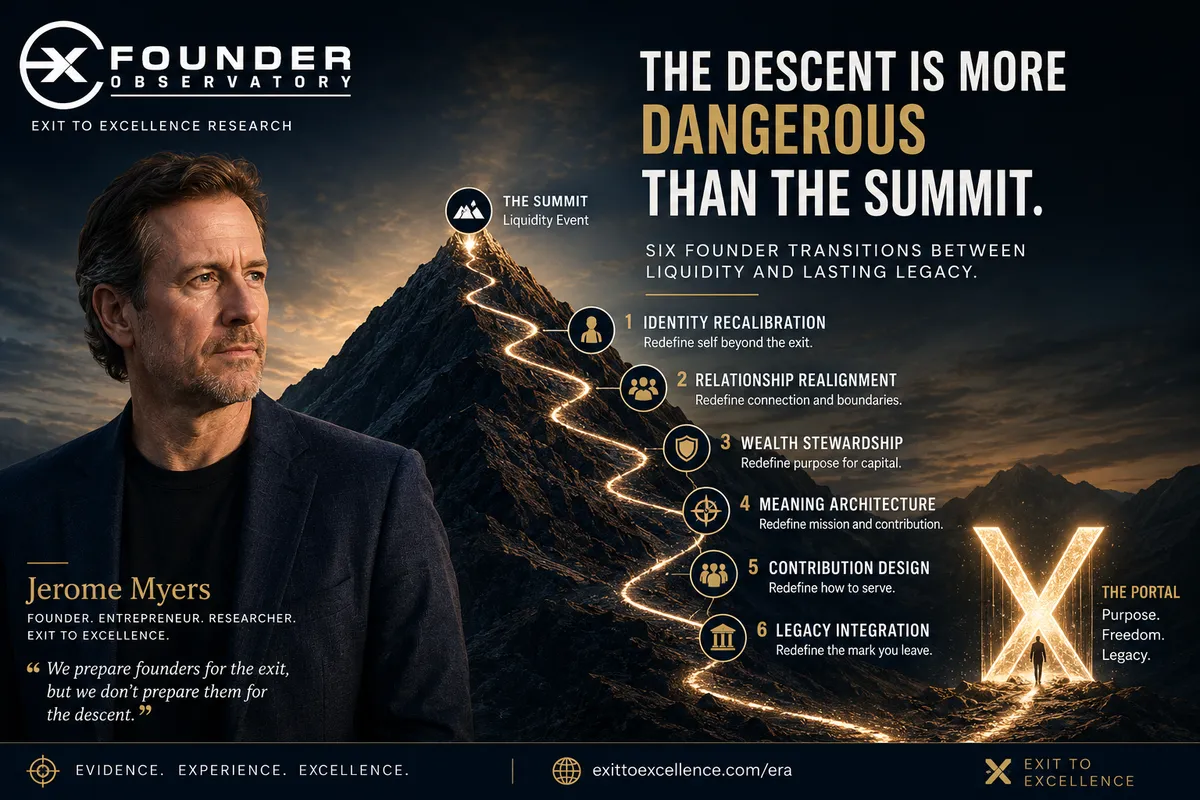
The Summit Gets the Celebration. The Descent Determines Whether the Exit Was Worth It.
Everybody takes the picture at the summit.
The signed agreement, the wire, the final announcement, and the first morning without an operating problem all make a clean story. Years of risk appear to resolve into one visible moment. The founder has arrived.
But a summit is not a place to live. The work that follows is a descent: returning from an extraordinary event to an ordinary calendar, a changed relationship system, a body that may finally register the cost of the climb, and a life that can no longer borrow its direction from the company.
Calling that interval “the descent” is not a prediction of decline. It is a planning distinction. The skills that help a founder reach liquidity are not automatically the skills that help the founder absorb it. Speed, endurance, control, and concentrated sacrifice can be assets on the way up. On the way down, those same habits can prevent recovery, distort new commitments, and keep the founder attached to a role that has already ended.
“The problems post exit that are amplified by the liquidity event aren’t solved by the money that you get from the liquidity event.”
Jerome Myers | Hodge interview | 19:35
Money can settle a transaction. It cannot decide which relationships need repair, how much work should remain, whether the founder is resting or disappearing, or what deserves the next decade. Those are transition decisions. They require different equipment.
What the broader body of knowledge actually supports
The Founder Observatory’s current governed synthesis covers 400 transcripts. It is a qualitative body of knowledge, not a representative survey. The value is not a percentage of founders who struggle. The value is a set of recurring mechanisms, counterexamples, and planning questions that can be tested in a founder’s actual situation.
Several constructs in that synthesis describe the descent with more precision than the mountain metaphor alone.
1. Silence Shock / Absence Rehearsal: Time away while the business can still reach the founder does not simulate the absence that follows a real transfer. Work feedback loops supply requests, relevance, stimulation, and identity cues. Remove the feedback loop and a different experience becomes visible.
2. Achievement Identity Survives Liquidity: Financial sufficiency can arrive before the founder stops using achievement as a measure of worth. The money may be finished before the scorekeeping is.
3. Staged Identity Transfer: Full stop and full continuation are not the only options. A bridge role can preserve valued functions while operating load and old identity cues contract—provided the bridge has an end and does not become avoidance.
4. Relationship Recovery / Collateral Damage: The business may consume relational capacity long before the sale. The transition can create room for repair, but liquidity cannot do that work on the founder’s behalf.
5. Health as a Transfer Requirement: Sleep, recovery, stress, and deferred care can be borrowed against future capacity. A founder may reach closing financially stronger and physically depleted.
6. The N.E.X.T. as Experiment: Direction can be correct while the first vehicle is wrong. The next chapter is better tested through bounded commitments than declared as a new permanent identity.
These are research constructs, not verdicts. The corpus also contains counterevidence: some founders have strong non-work structures before exit; staged roles can prolong dependency; urgent decisions can be economically real; and a new company can be a genuine calling rather than an escape. The purpose of the model is to improve inquiry, not force every founder into the same story.
A successful transaction can still create a hard descent
“After four or five months, those sensations dissipated, and there was more confusion and uncertainty around what next. A lot of your identity, a lot of your connections, and a lot of your routine is around your whole workday.”
Kevin Nolan | exited founder | Your N.E.X.T. | June 21, 2026 | 03:24–04:07
Kevin Nolan was not describing a bad deal. He was describing the expiration of the transaction’s emotional momentum. The business had supplied structure, connection, and a reliable answer to what mattered today. Liquidity expanded his options before it replaced that orientation.
That distinction matters. If the founder interprets uncertainty as proof that the sale was a mistake, the next decision may be made to eliminate discomfort rather than express direction. If the advisor interprets wealth as evidence that the founder is ready, the human transfer can remain invisible until it appears as an impulsive investment, a strained relationship, an unwanted operating role, or a calendar filled faster than it can be examined.
“Seller’s remorse, big time. Regardless of the money, it is something.”
Mark Hartmann | exited healthcare founder and M&A adviser | Your N.E.X.T. | March 2, 2026 | 24:00–24:20
Mark Hartmann’s account does not establish how often seller’s remorse occurs. It establishes something narrower and more useful: a financially successful outcome and a difficult human experience can coexist. Price and preparedness are different variables.
The dangerous part is using ascent equipment on the way down
Founders are trained by the build. When uncertainty appears, they create a plan. When the calendar opens, they fill it. When identity becomes unstable, they acquire a new title. When the company no longer needs them, they find another system that will.
Those moves can be intelligent. They can also be reflexes. The problem is not action. The problem is action taken before the founder knows what function the action is performing.
“Whatever you think is going to happen after that, it is going to be way different. You are definitely not going to be needed at that company, no matter how indispensable you think you are right now. You better have an idea of where you are going to go next.”
Roland Frasier | exited founder and investor | Your N.E.X.T. transcript | 46:10–46:39
A next direction matters. But a title is not the same as direction, and activity is not the same as alignment. A new venture may be the right experiment. A board seat may be meaningful contribution. A period of recovery may be productive. The descent becomes dangerous when the founder needs the first answer to be permanent because uncertainty feels intolerable.
Different equipment for the descent
The Exit Expedition model treats the descent as a distinct operating environment. Preparation is not a promise that the founder will avoid grief, uncertainty, or fatigue. It is an effort to preserve enough capacity and honesty to respond without surrendering choice.
1. Rehearse absence: Test time away with the feedback loop actually removed. No approvals, no rescue calls, no checking the system in secret. Notice what the business does—and what happens inside the founder when it cannot find them.
2. Name what the company supplies: Inventory role, rhythm, relationships, recognition, stimulation, and proof of usefulness. A next chapter cannot replace functions that remain unnamed.
3. Separate recovery from direction: Exhaustion can make rest look like loss of ambition. Silence can make any opportunity look meaningful. Give the nervous system and the calendar enough room to distinguish depletion from desire.
4. Use bridge roles deliberately: Retain selected functions for a defined period only when the role has boundaries, authority, compensation, and an exit. A bridge should transfer identity, not preserve dependency indefinitely.
5. Run bounded experiments: Test teaching, investing, advising, creating, philanthropy, or another venture at a scale that produces evidence without requiring a new identity on day one.
6. Protect the relationship and health systems: Do not wait for closing to ask what the climb cost. Health and relational capacity are transfer conditions, not rewards to address after the transaction.
What this research does—and does not—claim
This release is an authored qualitative synthesis. The 400-transcript corpus was used to identify recurring constructs and counterevidence. The founder statements quoted here are attributed, timestamped accounts selected to illuminate mechanisms in context. The Exit Expedition supplies the organizing model.
The evidence supports a planning proposition: the post-liquidity environment can remove structures faster than a founder replaces them, and different mechanisms require different responses. It does not support a percentage of founders affected, a universal emotional sequence, a clinical diagnosis, or the claim that every difficult feeling after exit is caused by the transaction.
The summit deserves celebration. The descent deserves design.
See which founder, enterprise, and post-exit risks may be connected in your situation: Complete the Exit Risk Assessment